The debate within the U.S. Federal Reserve is becoming increasingly transparent, and the differences of opinion among senior policymakers are beginning to influence global financial markets in their own right. Despite the decision to leave interest rates unchanged, several Federal Reserve officials have publicly stated that they would have preferred a more restrictive monetary policy stance. At London Hub Global, we believe these comments are just as significant as the policy decision itself, as they provide investors with valuable insight into the likelihood of future policy adjustments and allow markets to recalibrate expectations well in advance.
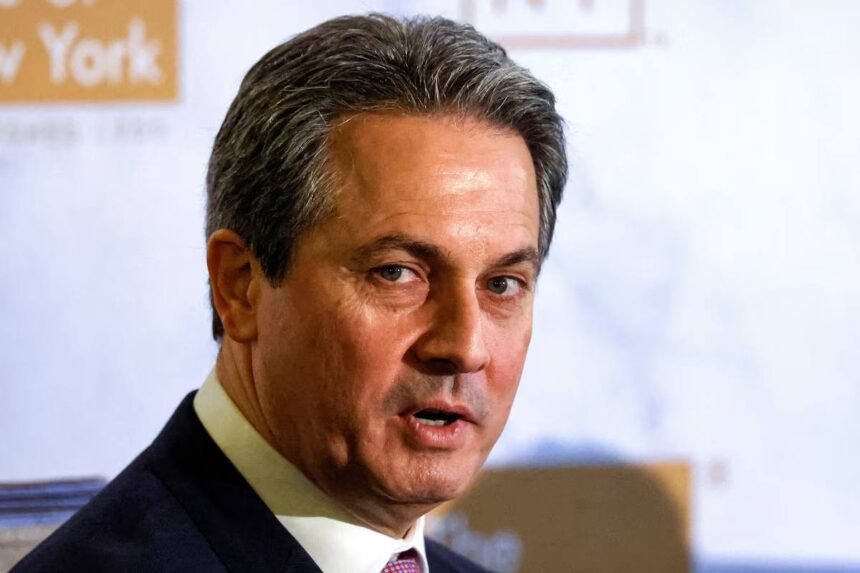
Federal Reserve Bank of St. Louis President Alberto Musalem confirmed that he supported raising the federal funds rate by 25 basis points at the latest policy meeting. In his view, current borrowing costs are no longer sufficiently restrictive to contain inflation, while the probability of inflation remaining above the Federal Reserve’s 2% target over the coming year remains uncomfortably high. Analysts note that his position reflects growing concern among a number of Federal Reserve officials about the persistence of inflationary pressures. We view this as a clear indication that additional monetary tightening remains firmly on the table despite the July pause.
According to Musalem, taking gradual action today would prove significantly less costly than being forced into much sharper rate increases later if inflation accelerates again. He argued that earlier intervention enables central banks to avoid more disruptive policy moves and reduces the economic costs of restoring price stability. This reasoning has long been regarded as one of the fundamental principles of modern central banking. At London Hub Global, we analyze these remarks as an effort to prepare financial markets for the possibility of another rate increase should upcoming inflation data fail to demonstrate convincing progress toward price stability.
At its July 29 meeting, the Federal Reserve kept the federal funds target range unchanged at 3.5% to 3.75%. Nevertheless, three members of the Federal Open Market Committee voted in favor of raising rates, marking one of the most notable internal divisions seen in recent years. At the same time, Federal Reserve Chair Kevin Warsh largely declined to provide explicit guidance regarding future policy decisions, instead leaving financial markets to interpret incoming economic data independently. Such an approach significantly increases market sensitivity to every new release on inflation, employment, consumer spending, and broader economic activity.
Musalem also emphasized the current resilience of the U.S. economy. Financial conditions continue to support economic growth, asset prices remain elevated, and the labor market has stabilized with solid wage growth and unemployment remaining close to its long term equilibrium. For many Federal Reserve officials, continued labor market strength provides sufficient flexibility to consider additional rate increases without immediately threatening economic expansion. At London Hub Global, we emphasize that robust economic activity simultaneously supports growth while making the fight against inflation more challenging, as resilient consumer demand can slow the pace of price moderation.
Another central theme of Musalem’s remarks was inflation expectations. He warned that maintaining public confidence in the Federal Reserve’s commitment to returning inflation to its 2% objective remains essential for long term economic stability. Should households and businesses begin expecting persistently higher inflation, those expectations could become self reinforcing through stronger wage demands, higher pricing strategies, and broader increases in service costs. He also rejected the argument that monetary policy should remain more accommodative simply because future productivity gains driven by artificial intelligence may eventually ease inflationary pressures. In his assessment, policy decisions must address today’s inflation risks rather than rely on uncertain technological benefits that may emerge years from now.
For the United Kingdom and London, these developments carry direct significance. A higher probability of additional U.S. rate increases could strengthen the U.S. dollar, reshape global capital flows, and place upward pressure on financing costs across international markets. For London’s position as one of the world’s leading financial centers, this translates into heightened activity across foreign exchange, fixed income, and investment markets, while British institutions must increasingly account for tighter U.S. financial conditions when evaluating asset prices, cross border financing, and long term investment strategies. British companies with substantial exposure to the U.S. economy will also continue to monitor Federal Reserve policy closely, as the cost of capital remains a critical driver of corporate expansion and investment decisions.
At London Hub Global, we view Alberto Musalem’s comments as an important indicator of the evolving direction of U.S. monetary policy. If inflation remains above target, the likelihood of another interest rate increase will continue to rise, requiring financial markets to adapt to a prolonged period of elevated borrowing costs. We believe investors should pay particularly close attention to upcoming inflation and labor market data, as these indicators will ultimately determine the Federal Reserve’s next steps and shape the trajectory of global financial markets over the coming quarters.